GSTR-9 Annual Return & GSTR-9C Reconciliation Services in Delhi
Comprehensive Annual GST Compliance, ITC True-Up, Turnover Reconciliation & Notice Prevention by Chartered Accountants
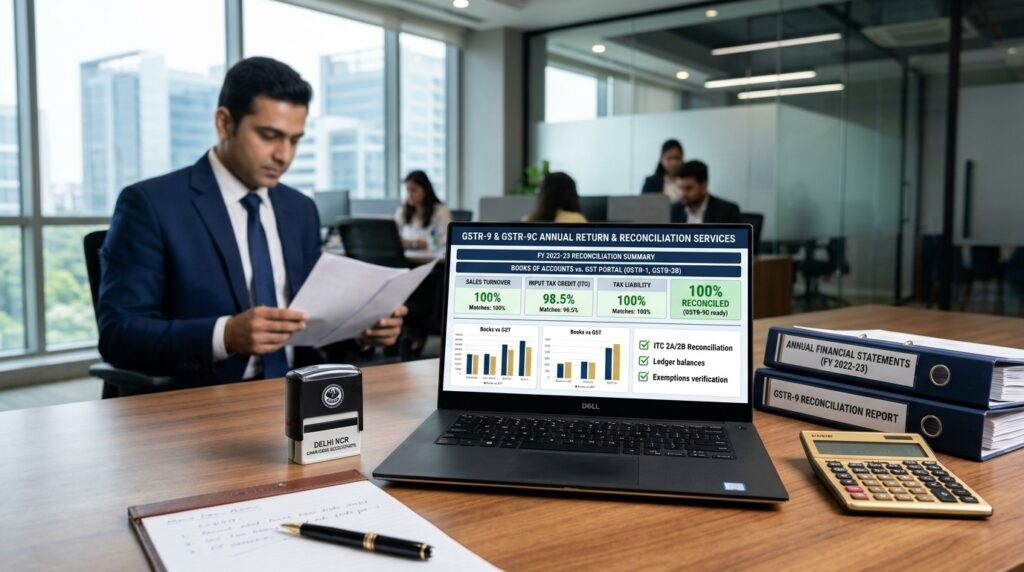
Every registered regular GST taxpayer in India must close their annual indirect tax books through the mandatory filing of Form GSTR-9 (Annual Return) and, where turnover exceeds statutory thresholds, the Form GSTR-9C (Reconciliation Statement). Unlike monthly or quarterly returns, the annual return is a cumulative consolidation that serves as the final statutory opportunity to true-up outward supplies, reconcile tax payments, claim eligible remaining credits, and reverse inadmissible Input Tax Credit (ITC) before the tax department initiates scrutiny.
Ankush Aggarwal & Associates is a reputed Chartered Accountant (CA) firm in Delhi NCR delivering meticulous GSTR-9 annual return filing and GSTR-9C reconciliation services. Operating from Mayur Vihar Phase 1, our CA professionals assist corporate houses, partnership firms, manufacturers, traders, and service providers across Delhi, Noida, Gurgaon, and Ghaziabad in achieving flawless annual GST closure under Section 44 of the CGST Act, 2017 read with Rule 80 of the CGST Rules.
Who Must File GSTR-9 and GSTR-9C? Statutory Thresholds
The requirement to file annual returns is determined by aggregate annual turnover during the relevant financial year:
| Aggregate Annual Turnover | Form Required | Filing Nature & Requirement |
|---|---|---|
| Turnover up to ₹2 Crores | Form GSTR-9 | Optional / Exempt: Taxpayers with annual turnover up to ₹2 Cr are exempt from mandatory GSTR-9 filing pursuant to CBIC notifications. However, voluntary filing is recommended if significant tax mismatches exist. |
| Turnover exceeding ₹2 Crores up to ₹5 Crores | Form GSTR-9 | Mandatory: Filing GSTR-9 is strictly compulsory. Late filing attracts non-waivable statutory penalties. |
| Turnover exceeding ₹5 Crores | Form GSTR-9 + Form GSTR-9C | Mandatory Both: Taxpayer must file GSTR-9 and a self-certified/CA-reconciled GSTR-9C reconciliation statement reconciling audited annual financial accounts with GST portal filings. |
| Composition Scheme Dealers | Form GSTR-9A | Simplified annual return for composition taxpayers (waived for specific recent financial years by CBIC notifications). |
Note: Casual taxable persons, non-resident taxable persons, Input Service Distributors (ISD), and persons deducting TDS/TCS under Sections 51 and 52 are exempt from filing GSTR-9.
Structure of Form GSTR-9: What Gets Reported?
Filing an accurate GSTR-9 requires populating 6 comprehensive parts spread across 19 tables. A mistake in any table can trigger automatic department scrutiny under Section 61 (Scrutiny of Returns):
- Part I (Tables 1-3): Basic registration details, financial year, legal name, and trade name.
- Part II (Tables 4-5): Outward supplies and advances on which tax is payable (B2B, B2C, exports, SEZ supplies, RCM inward supplies) and supplies on which tax is not payable (exempted, nil-rated, non-GST).
- Part III (Tables 6-8): Detailed breakdown of Input Tax Credit (ITC) availed during the financial year — bifurcated into inputs, capital goods, and input services — alongside comparison with auto-populated GSTR-2A/2B and reversals under Rules 37, 38, 42, 43, and Section 17(5).
- Part IV (Table 9): Details of tax paid as declared in returns filed during the financial year (cash vs credit payment).
- Part V (Tables 10-14): Transactions of the previous financial year declared in returns of April to October/November of the following financial year (late adjustments, debit notes, credit notes, ITC reclaimed).
- Part VI (Tables 15-19): Other information including refund claims, demands, supplies received from composition dealers, deemed exports, HSN-wise summary of outward and inward supplies, and late fee payable.
Form GSTR-9C: Self-Certified Reconciliation Statement
When aggregate turnover crosses ₹5 Crores, filing Form GSTR-9C becomes compulsory. GSTR-9C is an intricate reconciliation mechanism between two distinct sets of records:
- Audited Financial Statements (Balance Sheet, Profit & Loss Account, and Notes prepared under GAAP/Ind-AS)
- Annual Return (Form GSTR-9) filed on the GST common portal
Our Chartered Accountants perform rigorous line-by-line reconciliations to explain variances, including:
- Reconciliation of gross turnover reported in P&L vs taxable turnover reported in GST returns.
- Unbilled revenue at the beginning vs the end of the year.
- Advances received for services vs invoice raised adjustments.
- Deemed supply valuation under Schedule I of CGST Act (related party transactions without consideration).
- Reconciliation of rate-wise tax liability and additional tax payable through Form GST DRC-03.
- Reconciliation of Input Tax Credit booked in expense ledgers vs ITC claimed in GSTR-9.
Our 5-Step Annual GST Return Audit & Filing Workflow
Step 1: Multi-Dimensional Data Compilation
We extract and compare 12 months of GSTR-1, GSTR-3B, auto-drafted GSTR-2B, purchase registers, sales registers, and audited trial balances to spot discrepancies before the system does.
Step 2: ITC Reconciliation & Ineligible Credit Reversal
We identify blocked credits under Section 17(5) (motor vehicles, food & beverages, personal use), compute reversal for exempt supplies under Rule 42 & 43, and verify supplier 180-day payment compliance under Rule 37.
Step 3: Tax Liability True-Up & DRC-03 Computation
If outward supplies or RCM liabilities were underreported during monthly filings, we compute the tax and applicable statutory interest u/s 50, facilitating voluntary discharge via DRC-03 to avoid 100% penalty imposition under Section 73/74.
Step 4: Table-by-Table Drafting & Management Review
Our CA team prepares the full draft of GSTR-9 and GSTR-9C with explanatory footnotes. We review every discrepancy with your management and finance team before final upload.
Step 5: Portal Submission & Audit Trail Archival
Filing with DSC/EVC, generating the final acknowledgement receipt, and creating an organized audit docket for future departmental assessments or GST audits.
Statutory Due Date and Late Filing Penalties
Under Section 44(1), the statutory due date for filing GSTR-9 and GSTR-9C is 31st December following the close of the financial year (unless extended by CBIC notification).
Consequences of Late Filing:
- Late Fee for GSTR-9 (Section 47(2)):
- Turnover up to ₹5 Crores: ₹50 per day (₹25 CGST + ₹25 SGST), subject to a maximum cap of 0.04% of turnover (0.02% CGST + 0.02% SGST).
- Turnover between ₹5 Crores and ₹20 Crores: ₹100 per day (₹50 CGST + ₹50 SGST), subject to a maximum cap of 0.04% of turnover.
- Turnover above ₹20 Crores: ₹200 per day (₹100 CGST + ₹100 SGST), subject to a maximum cap of 0.50% of turnover (0.25% CGST + 0.25% SGST).
- General Penalty for GSTR-9C: Failure to file GSTR-9C where required attracts a general penalty under Section 125, which can extend up to ₹50,000 (₹25,000 CGST + ₹25,000 SGST).
- Department Scrutiny: Non-filing or late filing automatically flags your GSTIN for comprehensive scrutiny (ASMT-10) and potential audit under Section 65.
Frequently Asked Questions on GSTR-9 & GSTR-9C Filing
1. Can GSTR-9 be revised once it is filed on the GST portal?
No. Unlike income tax returns, the GST portal provides no provision to revise Form GSTR-9 once submitted. Any errors, omissions, or incorrect declarations remain permanent and can only be explained through replies to departmental scrutiny notices. This makes professional CA review before filing indispensable.
2. Can I claim missed Input Tax Credit (ITC) directly in GSTR-9?
No. GSTR-9 is an informational return. Unclaimed ITC of a financial year cannot be availed through GSTR-9. Under Section 16(4), any missed ITC could only be claimed in monthly GSTR-3B filed up to 30th November following the end of the financial year. However, additional tax liabilities can and must be discharged via DRC-03 with GSTR-9.
3. Is GSTR-9C certification by a practicing Chartered Accountant still mandatory?
Effective from FY 2020-21 onwards, the government amended Section 44 to allow taxpayers to self-certify Form GSTR-9C. However, due to complex mathematical reconciliations between balance sheet ledgers and GST tables, most businesses with turnover above ₹5 Crores engage practicing Chartered Accountants like Ankush Aggarwal & Associates to prepare and verify the reconciliation to avoid costly notice assessments.
4. What happens if there is a difference between GSTR-1 and GSTR-3B turnover?
Differences between GSTR-1 (tax declared) and GSTR-3B (tax paid) must be reconciled in Table 4 and Table 9 of GSTR-9. If tax was short-paid in GSTR-3B, the differential tax along with interest u/s 50 must be paid via Form DRC-03 at the time of filing GSTR-9.
5. Is GSTR-9 mandatory if my business had zero sales or was inactive?
If your aggregate turnover across PAN exceeded ₹2 Crores, filing GSTR-9 is mandatory even if business activity in a specific GSTIN was minimal. If turnover was below ₹2 Crores, you benefit from the waiver. Nil annual return facility is available for completely inactive registered persons.
Ensure Accurate, Notice-Proof Annual GST Return Filing
Let seasoned Chartered Accountants reconcile your financial statements, verify ITC eligibility, and file GSTR-9 & GSTR-9C with complete accuracy.
Ankush Aggarwal & Associates | Office: A4, Acharya Niketan, Mayur Vihar Phase 1, Delhi – 110091 | Email: info@aaaa.co.in